
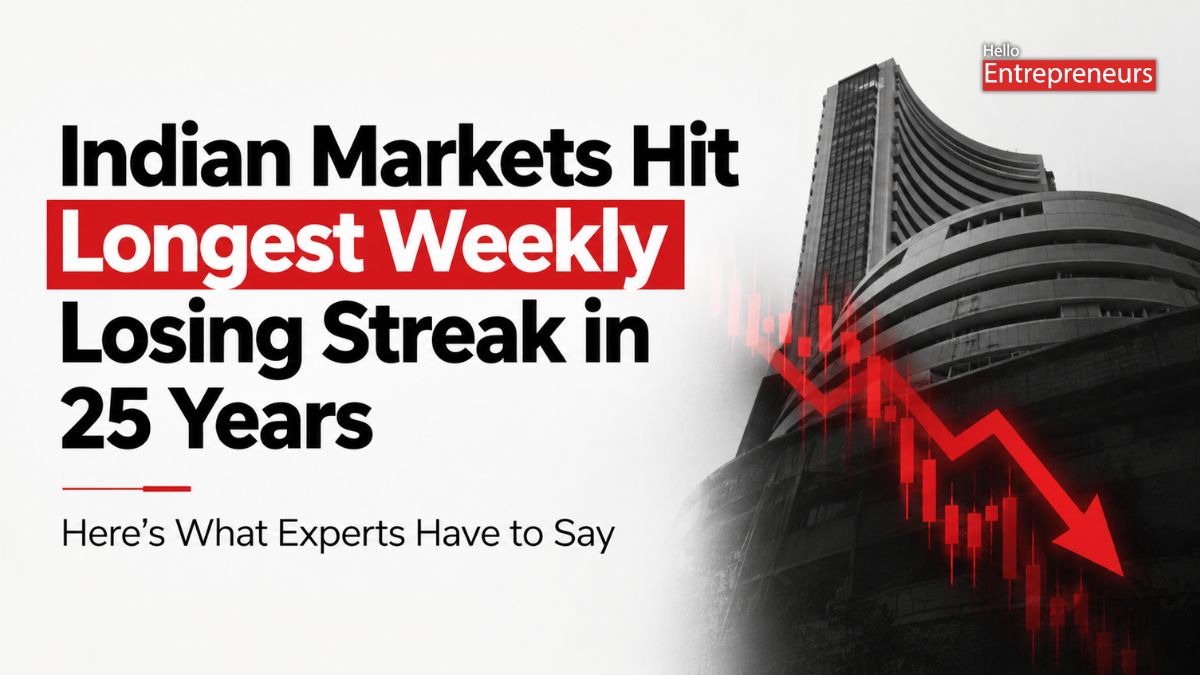
Mumbai, 13 October: Indian stock markets are facing one of their most challenging periods in recent years, as persistent foreign investor selling, expensive crude oil and rising global borrowing costs have weighed on investor confidence. The Nifty 50 and BSE Sensex recorded eight consecutive weeks of losses, marking their longest weekly losing streak in 25 years, before a rebound in early October brought the decline to an end.
During the eight-week period, the Nifty 50 declined 8.7%, while the Sensex fell 8.4%. The sell-off also affected broader markets, with mid-cap and small-cap stocks facing considerable pressure. According to market reports, the Nifty had fallen nearly 13% in 2026 at the beginning of October, highlighting the scale of the correction.
However, the latest market movements suggest that investors are still searching for clear signs of a sustained recovery. On October 13, the Nifty 50 gained 1.6% to close at 22,721.95, while the Sensex advanced 1.54% to 73,033.78, supported by strong buying in information technology stocks following encouraging quarterly earnings from HCL Technologies.
Despite this recovery, investors remain concerned about whether the market can sustain its gains amid continued foreign fund outflows and uncertainty surrounding inflation, interest rates and corporate earnings.
Foreign Investor Selling and Global Pressures Drive the Correction
Foreign portfolio investor (FPI) selling has emerged as one of the biggest factors behind the market decline. According to reports published by foreign investors withdrew approximately $27.8 billion from Indian equities during 2026 by early October. They sold shares worth Rs 45,536 crore in September alone, intensifying pressure on benchmark indices.
Higher US Treasury yields have made dollar-denominated investments more attractive, encouraging global investors to reconsider their exposure to emerging markets. The US 10-year Treasury yield climbed towards 5.3%, while Brent crude prices remained above $100 per barrel amid geopolitical tensions.
For India, higher crude prices are particularly concerning because the country depends heavily on imported oil. Expensive energy can increase transportation and manufacturing costs, put pressure on inflation and weaken the rupee. Higher borrowing costs can also affect business expansion and consumer spending.
Weak monsoon conditions and expectations of tighter monetary policy have added to these concerns. Together, these factors have created a challenging environment for companies and investors, even as India’s long-term economic prospects continue to attract attention.
Hemant Sood Sees a Flow-Driven Correction, Advises Caution
Hemant Sood, Founder and Managing Director of Findoc, believes the current correction is primarily driven by capital flows rather than a fundamental breakdown in the Indian economy.
“My view is that this is a flow-driven correction rather than a breakdown in fundamentals,” Sood said.
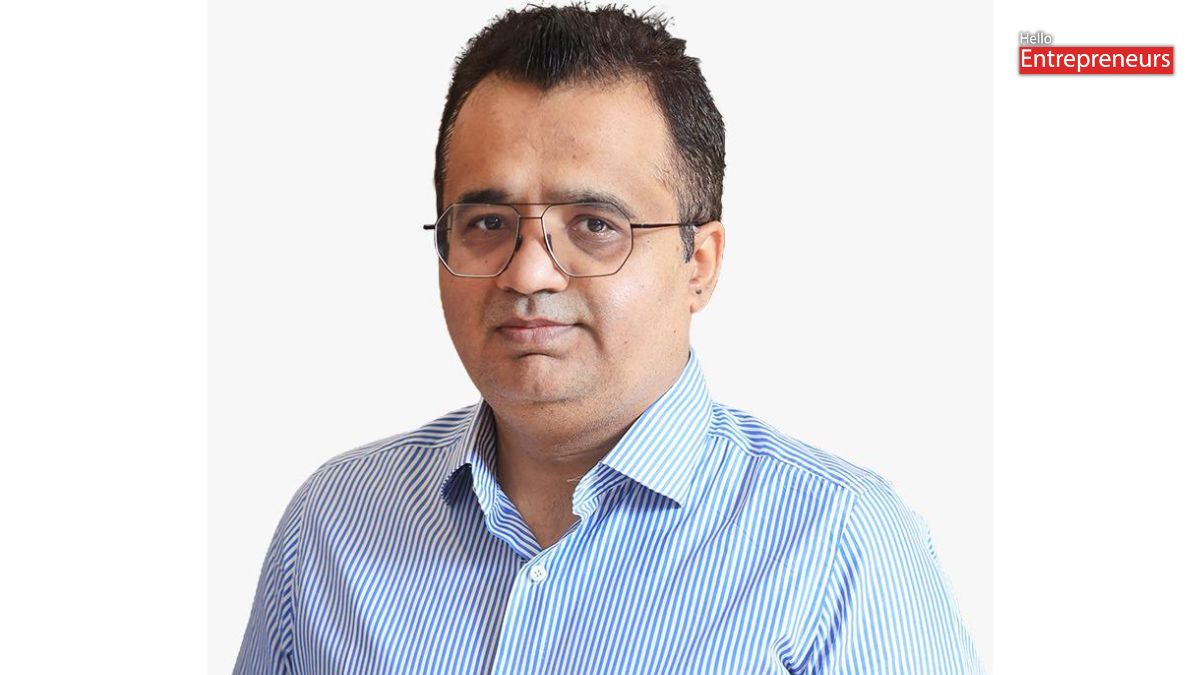
He pointed to domestic institutional investors (DIIs) as an important source of support during the downturn. According to the provisional NSE data cited in his inputs, DIIs purchased equities worth Rs 76,030 crore in September, helping absorb foreign investor selling.
Sood believes investors should continue their systematic investment plans (SIPs), spread lump-sum investments over three to six months, reduce leverage and favour large-cap companies with low debt and more reasonable valuations.
He also cautioned that the recent rebound does not necessarily confirm that the market has reached its bottom. Crude oil prices, US bond yields and second-quarter corporate earnings are likely to influence the next phase of market movement.
His advice highlights the importance of maintaining investment discipline instead of attempting to predict short-term market movements.
Ronit Kar Highlights Global Repricing and the Role of GIFT IFSC
Ronit Kar, CEO of VTI IFSC (ViewTrade International IFSC Private Limited), believes the market decline reflects a broader reassessment of global risk and investment opportunities.
“The current market decline is less about a single trigger and more about a reset in global risk appetite,” Kar said.
He also highlighted how artificial intelligence is changing traditional technology and services businesses, prompting investors to reassess growth expectations, pricing models and future earnings potential. Geopolitical uncertainty has further encouraged investors to diversify towards assets perceived as safer, including gold.
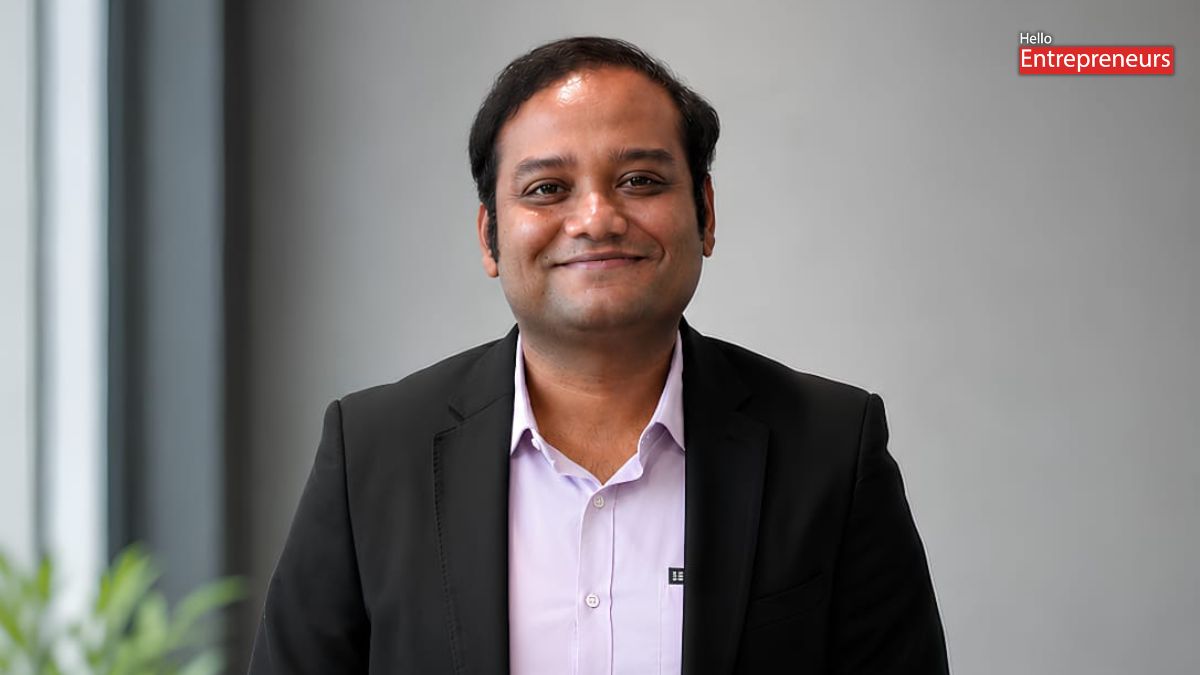
From Kar’s perspective, the current phase represents repricing and capital reallocation rather than a broad reassessment of India’s long-term growth potential.
He sees opportunities in improving access to international markets for Indian investors and creating more efficient channels for global capital to enter India. GIFT IFSC, India’s international financial services centre in Gujarat, could play an increasingly important role in facilitating cross-border investment.
Kar remains cautiously optimistic about Indian equities towards the end of the calendar year, supported by domestic growth, government capital expenditure, manufacturing activity and India’s expanding role in global supply chains. However, he expects the next phase of market performance to be more selective, with company earnings and valuations playing a greater role in determining stock returns.
Archana Khosla Burman Flags Pressure on Retail and Textile Businesses
The impact of the market downturn extends beyond stock prices. Archana Khosla Burman, Co-Founder of ZONE, highlighted the potential consequences for businesses operating in consumer-facing industries, including retail and textiles.
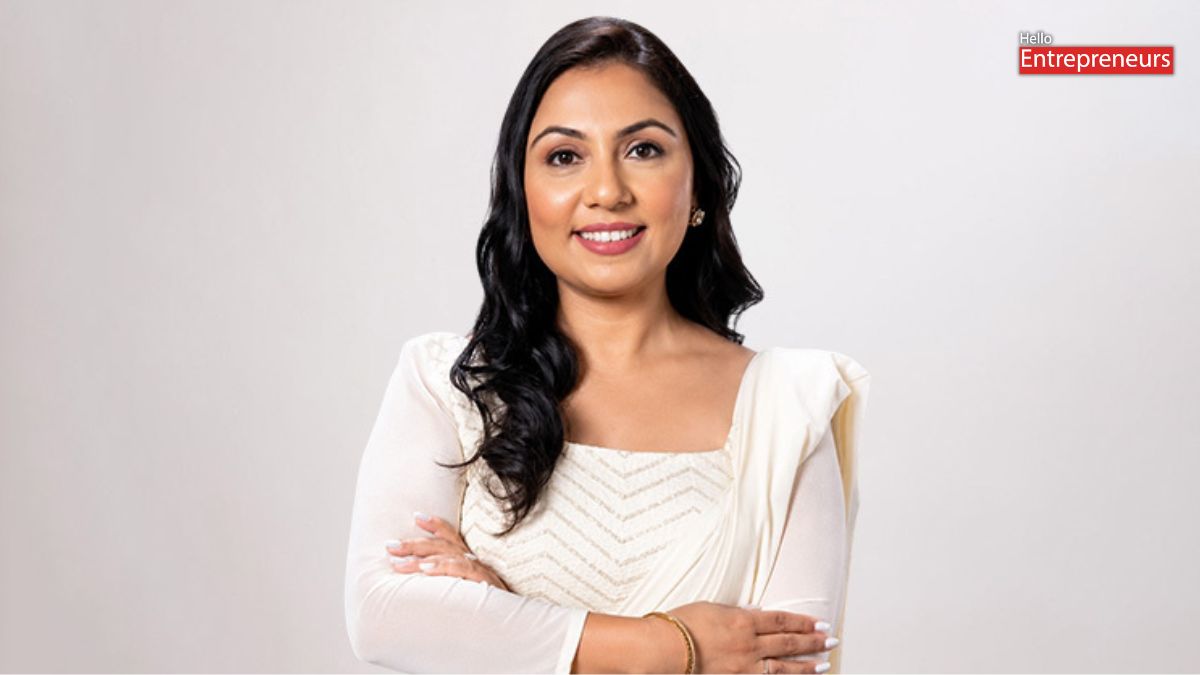
Weak consumer sentiment can affect household spending and put pressure on retail sales. Textile companies, meanwhile, may face challenges from fluctuating raw material prices, weaker export demand and uncertainty in global trade.
A prolonged period of market weakness can also affect business expansion by making capital more expensive or difficult to access. Companies planning new investments may reconsider their expansion timelines as financing conditions and demand expectations change.
Burman advises investors to avoid panic-driven decisions and maintain a long-term perspective.
“Although more corrections may occur in the markets, the downturn can present the opportunity to invest in strong companies at reasonable prices,” she said.
Her assessment reinforces the importance of evaluating individual businesses rather than treating every stock as equally affected by market volatility.
What Should Investors Watch Next?
The market’s immediate direction will depend on several factors, including foreign investment flows, crude oil prices, the rupee’s performance, inflation trends and second-quarter earnings.
Domestic institutional investors have helped cushion the impact of foreign selling, but continued outflows could limit the strength of any recovery. Corporate earnings will also be important in determining whether lower stock prices are supported by improved valuations or reflect deeper concerns about future profitability.
For retail investors, experts recommend diversification, disciplined investing and careful evaluation of company fundamentals. Reducing excessive leverage and avoiding decisions driven by short-term market movements can help manage risk during uncertain periods.
The end of the eight-week losing streak offers some relief, but it does not establish that the correction is over. As global economic pressures continue, the market is likely to reward selectivity, financial strength and sustainable earnings rather than momentum alone.
For investors, the key question is no longer simply when the market will recover, but which businesses are best positioned to withstand the current uncertainty and deliver sustainable growth over the long term.