
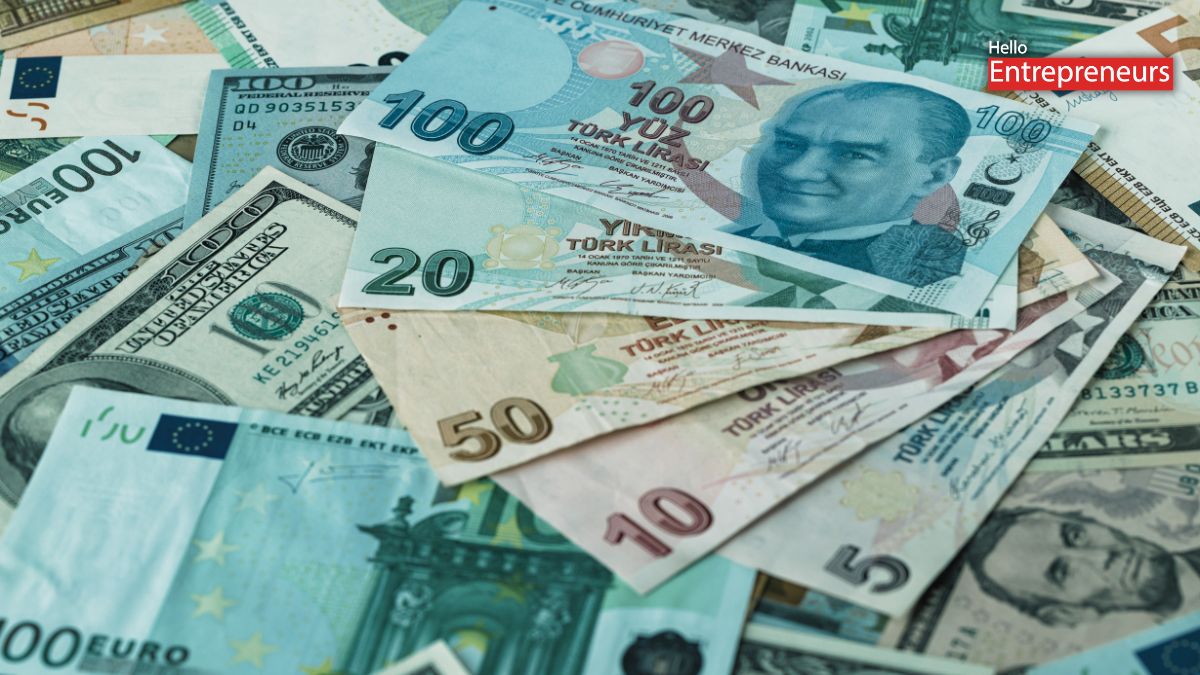





New Delhi: The Reserve Bank of India (RBI)’s attempt to shore up India’s forex reserves through the Indian diaspora has been a massive success, with the Foreign Currency Non-Resident (Bank) (FCNR-B) deposit scheme attracting inflows of over $65 billion before the August 31 deadline set to accept deposits. This mobilization is far higher than the previous FCNR(B) scheme by the RBI, which was announced in 2013, where nearly $26 billion flowed into the market.
The FCNR(B) scheme was launched as a way to bolster foreign exchange reserves due to the increasing weakness of the Rupee as against the dollar, which has reached historic lows due to the prolonged West Asia conflict and the resultant price rises in securing energy supplies.
For the government, this development shows how India’s 35 million-strong diaspora remains connected to their roots, helping in bailing out the government as these deposits will help boost India’s forex reserves while helping to stabilize the Rupee and improve liquidity with commercial banks with stable, medium- to long-term foreign currency funding sources.
“While there may be valid reasons to justify an early closure [of the FCNR (B) scheme], the most likely reason could be that the target for FCNR (B) mobilisation has already been achieved with inflows at $57 billion. And another $25-30 billion could easily flow in the remaining days of August, taking the total collections to around $85 billion,” Soumya Kanti Ghosh, group chief economic advisor, State Bank of India, said in a research note.






