
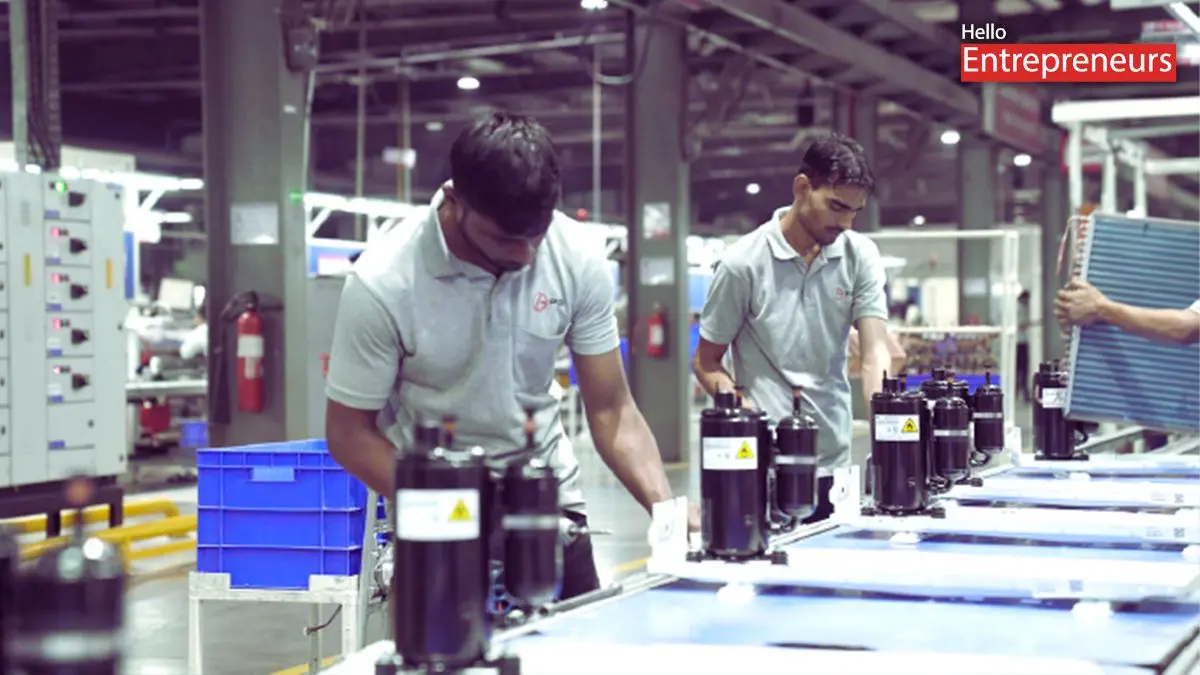





New Delhi: Noida-based electronic contract manufacturer PG Electroplast Limited (PGEL)’s shares fell almost 35% after the company reported a 20% decline in its net profit from Rs.84 crore in Q1 FY25 to Rs.67 crore in the corresponding quarter this year. The company has attributed this to rising supply costs and thinner margins, a pattern similar to its competitors in the niche.
“The early arrival of the monsoon impacted seasonal sales for Room ACs, making Q1 a more subdued start to the year. However, underlying demand indicators remain robust, and we see significant long-term potential given the relatively low penetration levels in core categories like Room ACs and Washing Machines. Capital efficiency remains a core operating principle and all capex decisions are guided by sustainable profitability metrics and long-term value creation. While near-term growth may moderate, our medium and long-term outlook remains strong” Vishal Gupta, MD Finance at PG Electroplast said.
Despite this, some analysts remain upbeat about the stocks future outlook. Nuvama has reiterated its ‘buy’ rating on the stock, though it has slashed its target price based on the current price movements.
“While April was robust (up 70 per cent YoY), May sales moderated to 18 per cent growth, and June and July suffered a sharp order cancellations (down 70 per cent YoY), leading to adverse operating leverage. Revenue growth guidance for FY26 stands reduced to 18 per cent (earlier 30 per cent) along with Ebitda margin contraction of 125–150 bps, assuming: i) weak Q2, Q3 performance anticipation; ii) large inventory; and iii) softened demand. PGEL remains committed to its long-term FY28 revenue target of INR90bn based on 4–5x asset turns,” it said.
The company has been a stock market darling ever since its IPO launched in 2011. Its shares have risen a staggering 10,500% in the last five years, banking on the Make in India initiative, similar to its competitor Dixon Technologies. However, both companies are facing challenging times due to muted demand for electronics domestically, even though investors continue to stand by the company due to its strong market fundamentals.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Readers should conduct their own research or consult with a qualified financial advisor before making any investment decisions.





