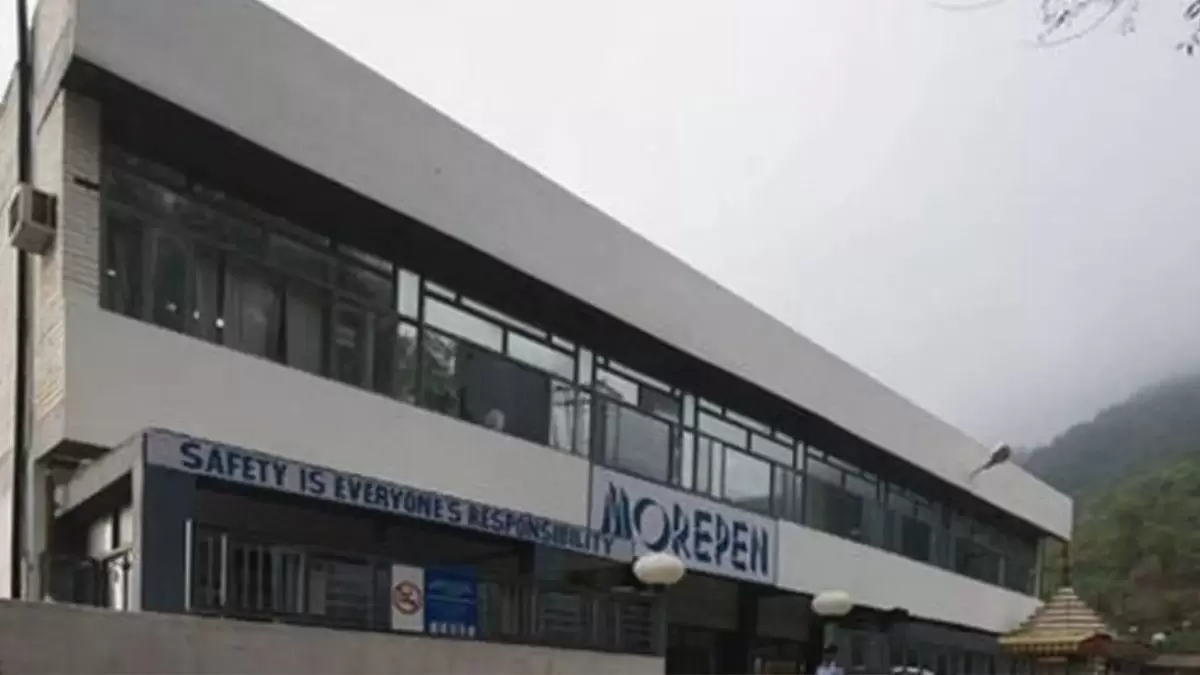




New Delhi: Gurugram-based pharmaceutical company Morepen Laboratories Ltd declares a Rs. 0.20 dividend for the first time in 23 years. The company also saw a 17% rise in the Earnings Per Share (EPS) to Rs. 2.20 from last year. Operational revenues jumped 10.11% Y-o-Y to Rs. 465.85 crore, even as the company’s profit before tax declined 39.07% to Rs. 25.71 crore from Rs. 42.20 crore last year. Consolidated net profit fell to Rs. 20.31 crore in Q4 FY25 from Rs. 28.74 crore in Q4 FY24.
The EBITDA declined by 11.32% YoY from Rs. 53 crore in Q4 FY24 to Rs. 47 crore in the same period.
Sushil Suri, Chairman & Managing Director of Morepen Laboratories Ltd., said: “This moment is symbolic – it’s not just about distributing profits; it’s about rewarding trust. We always believe in the “Joy of Growing Together”. Declaring a dividend after 23 years reflects our financial strength, operational excellence, and long-term vision of sharing and caring. Our shareholders have stood by us, and it’s time we give back.”
According to a company press release, Morepen’s API business contributed Rs. 989 crore while its Medical Devices achieved a turnover of Rs. 496 crore, growing 12% year-on-year. 72% of the company’s revenue comes from API exports to 80+ countries, and the company is aiming to boost its investments in product development and capacity expansions to propel the business forward.
Morepen’s API business continued to dominate, contributing Rs. 989 crore, while the Medical Devices segment surged to Rs. 496 crore, growing 12% year-on-year. With 72% of API revenue coming from exports across 80+ countries, Morepen is solidifying its position as a global pharmaceutical force. Investments in new product development, capacity expansion, and global regulatory approvals continue to propel the business forward.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Readers should conduct their own research or consult with a qualified financial advisor before making any investment decisions.