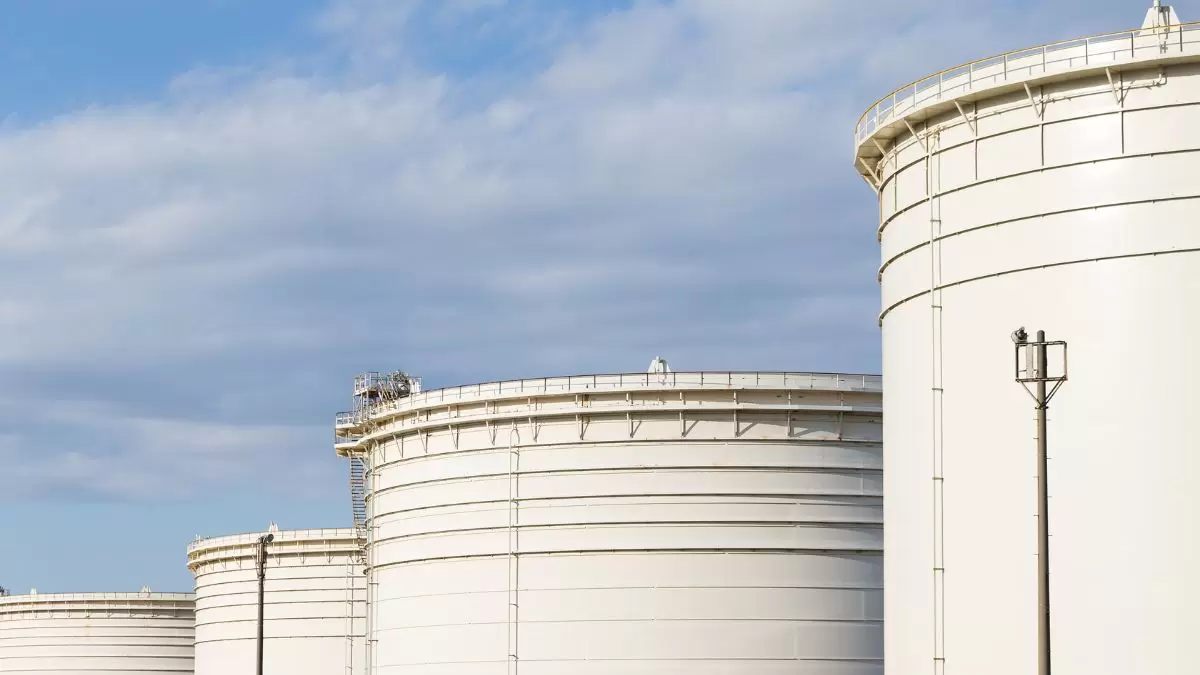





Mumbai: Aegis Logistics, an integrated Oil and Gas Logistics Company, has risen to Rs. 845.3 on the NSE on account of strong revenue growth and a 5% rise in Profit After Tax, even though revenues declined 9% Y-o-Y. This stock has even managed to outperform the Sensex (9.84%), and many analysts are upholding their ‘Hold’ rating for it.
With increased demand for e-commerce and institutional logistics, Aegis is one of the frontrunners in the niche, with a pan-India presence and its acquisition of 30 acres of land at JNPA and 7 acres in Kandla Port. It has also filed a Draft Red Herring Prospectus (DHRP) for an IPO for its subsidiary Aegis Vopak Terminals Ltd.
Add a healthy dividend payout of 36.3% every quarter, and this stock is slowly becoming every investor’s darling.
The Nifty Energy index, where Aegis is also included, has risen by 7.8% in one month, even as the stock gave 8.02% returns in the last month.
A report by the CBRE explains how third-party logistics suppliers like Aegis will see continued demand from diverse sectors like engineering and manufacturing, FMCG, and others besides e-commerce.
The report also warned about challenges that could delay project completion deadlines. Extended acquisition processes, growing land acquisition costs, complicated land ownership structures, and ongoing legal proceedings could slow progress and increase logistics costs in the short to medium run.