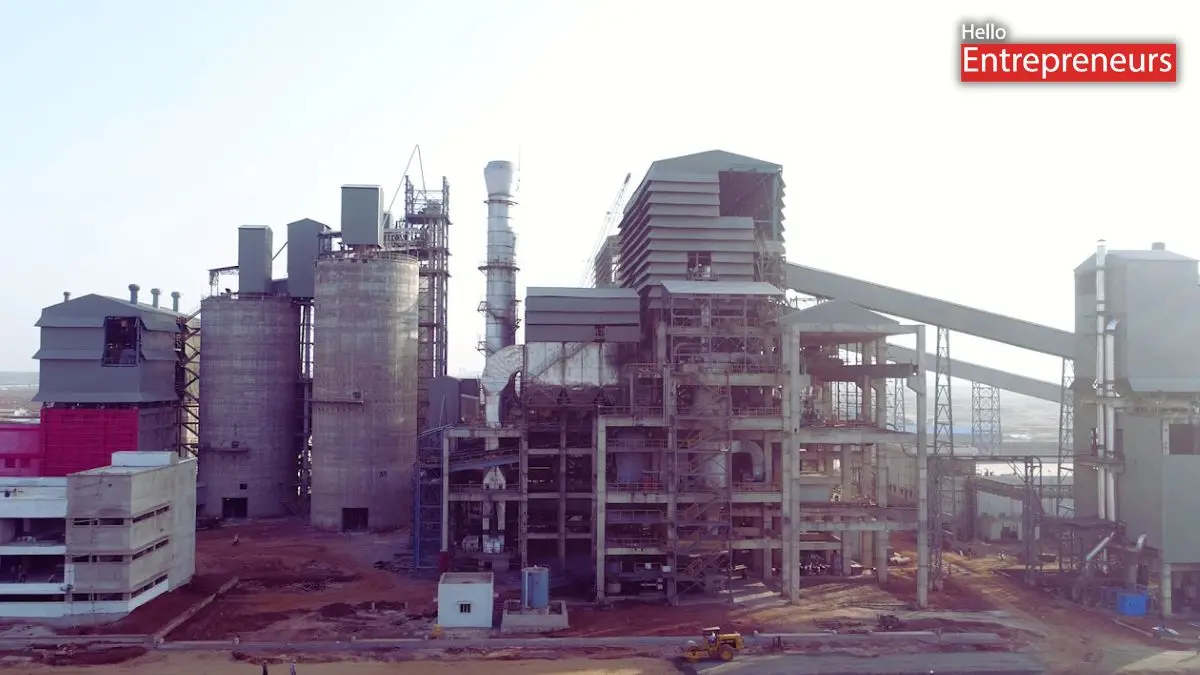




New Delhi: Investors are already looking forward to JSW Cement’s IPO, that’s set to open tomorrow, August 7. The Rs.3,600 crore public issue aims to raise funds for the company’s upcoming integrated cement plant in Nagaur, Rajasthan along with paying off a part of its Rs.2,700 crore net debt.
The company currently has an annual capacity of 21 MTPA, a fairly insignificant player in the industry dominated by UltraTech and Adani Cement, collectively have a capacity of 284 MTPA or a 48% market share. Even after its Nagaur plant is operationalised, the company doesn’t have much of a say in the market, instead focusing on doubling its capacity organically.
Parth Jindal, JSW Cement’s MD, candidly admitted in a press conference.
“If Ultratech or Adani wants to acquire anything, they can outmuscle us easily. Right now, we don’t have the ‘aukaat’, I would say, to challenge them in any acquisition,”
Even though he has a ‘deep admiration and respect’ for competition, his company will focus on its goals to grow organically, he concluded.
And for good reason. JSW Cement was established to complement the company’s steel operations, where the blast furnace slag- an otherwise discarded byproduct from the manufacturing process- is used as a natural cement additive to make it denser and stronger. The company currently does not have the financial muscle to take on the competition, yet wants to rise up its ranks in market share, hoping to triple its capacity to 60 MTPA in the next seven years.
The company’s cement plants are mostly concentrated in South India, and the company is hoping to make inroads into the North Indian market, where demand and prices are higher, though stronger competition could hurt margins.
Nevertheless, the company will find it challenging to deal with fluctuating input and freight costs, especially as these can have a big impact on margins. Even though demand will remain more or less consistent, the company has to find a way to increase its revenues, which have remained more or less flat, hovering around the Rs.6,000 crore mark. Concerningly, its profits have been sinking- from Rs.104 crore in FY23 to Rs.164 crore loss in FY25.
The company had initially aimed for a Rs.4,000 crore IPO, but watered it down to Rs.3,600 crore. Parth Jindal attributed this to the negative outlook of the cement industry, even as he blamed the big players in the market for ‘behaving irrationally’ to lower prices last year for booking revenues.
Nevertheless, the IPO is keenly awaited, with the grey market GMP being over 12% of the current share values. The IPO will have a fresh issue of Rs.1,600 crore with an Offer For Sale (OFS) component of Rs.2,000 crore by existing investors. The price band is between Rs.137-145 per share.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Readers should conduct their own research or consult with a qualified financial advisor before making any investment decisions.