
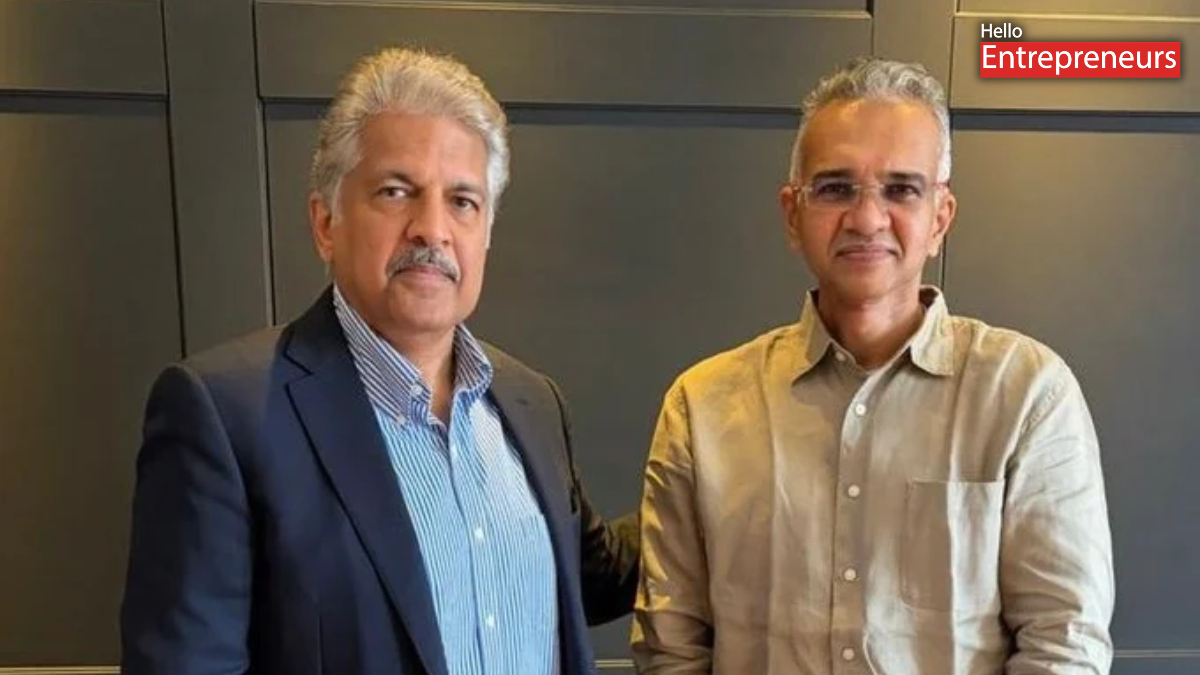
New Delhi: It seems industrialist Anand Mahindra was not expecting a digital payments app to be the reason for his phone changing hands when he was asked by a friend what he used to pay with on his phone. That’s what they did, though. After a lengthy chat with the organisation behind the nation’s retail payments backbone, the Mahindra Group chairman has publicly announced he’s stepping down to BHIM the government-backed app with the Unified Payments Interface (UPI) in India.
How it began
In a tweet on X, Mahindra has called it a friendly exchange. He was asked by a friend what payment application he used. Upon hearing this, she asked him “for what reason he didn’t use BHIM, our own app?” Mahindra said that he wasn’t aware of much about it. She replied with an introduction to him of someone he’d like to meet: Dilip Asbe, Managing Director and CEO of the National Payments Corporation of India (NPCI).
Asbe agreed to visit for a chat. It was a “illuminating” (to be generous) conversation, Mahindra said.
The railway analogy
Mahindra’s main post is an analogy that has spread like wildfire, to say the least. He said that most Indians are using PhonePe, Google Pay, Paytm or BHIM on a daily basis. These are app-like trains on an app-vey train network, he wrote. The tracks are provided by NPCI. “What an extraordinary railway India has built, he added.
What point is there in the apps people see being the front end? The platform that runs beneath them namely UPI is developed and operated by the country’s NPCI, one of the most important public digital infrastructures of the world, developed in concert with India’s government.The platform on which it runs, UPI, is developed and operated by NPCI, which is one of the most important pieces of public digital infrastructure in the world and quietly developed by NPCI in collaboration with India’s government.
The scale of the network
A breakdown of posts on X reveals that the UPI network facilitated more than 24 billion transactions during September 2026 alone. The number reflects India’s position as the largest real-time payments market globally, a position which other countries looking to implement instant payments often aim to reach. The numbers also confirm the reason behind Mahindra’s observation a system capable of managing billions of transactions per month requires reliable, neutral rails and not any one brand of consumer car.
A leader who stayed in the background
Asbe also got hit by Mahindra. In the NPCI’s summary of his posts, he noted how much the humility of the NPCI chief was inspiring, an attribute he attributed to Asbe’s mother, a teacher, and how the organisation was doing more than just seeking fame. In Mahindra’s own version of the story, those who built the tracks have seldom clamored for credit in fact, millions of people depend on them every day.
Why BHIM, and why it matters
BHIM Bharat Interface for Money is a UPI app developed by NPCI to demonstrate and promote the UPI. That’s in contrast to use of private-sector apps which are the majority of the apps that mark up the use. For Mahindra, the selection is partly as an expression of support for a home-grown vehicle and partly to allow the company to gain deeper insight into the system he now feels he knows better.
It has symbolic significance that he is swapping out for. A stellar business umbrella change in payment apps equates to a market share boost for the product that has long been trailing behind PhonePe and Google Pay. It is unclear if that will lead to wider usage, as habits, rewards, features and familiarity with merchants all play a role in choices of application to use.
Reaction online
Most of the feedback on the post was positive. Several users voiced the pride of having India’s payment infrastructure, and called UPI as being a successful home-grown initiative. Others shared their own longterm experience with BHIM, while many users requested that BHIM be made more user friendly, show greater usability and feature set, providing plenty of room to improve the consumer experience.
The bigger picture
Mahindra’s post is more of a reminder on how India’s payments is overlaid system. Certain apps may rise and fall in popularity but the rails cannot be changed, and interoperability is what enables a user on one app to pay another user on another app up and down the street.
It’s yet to be seen if Mahindra is inspiring others to follow suit with BHIM. The obvious take-home message here is that NPCI, and the unheard of railway behind the daily transactions in India, has got the attention of the public again in one single discussion.