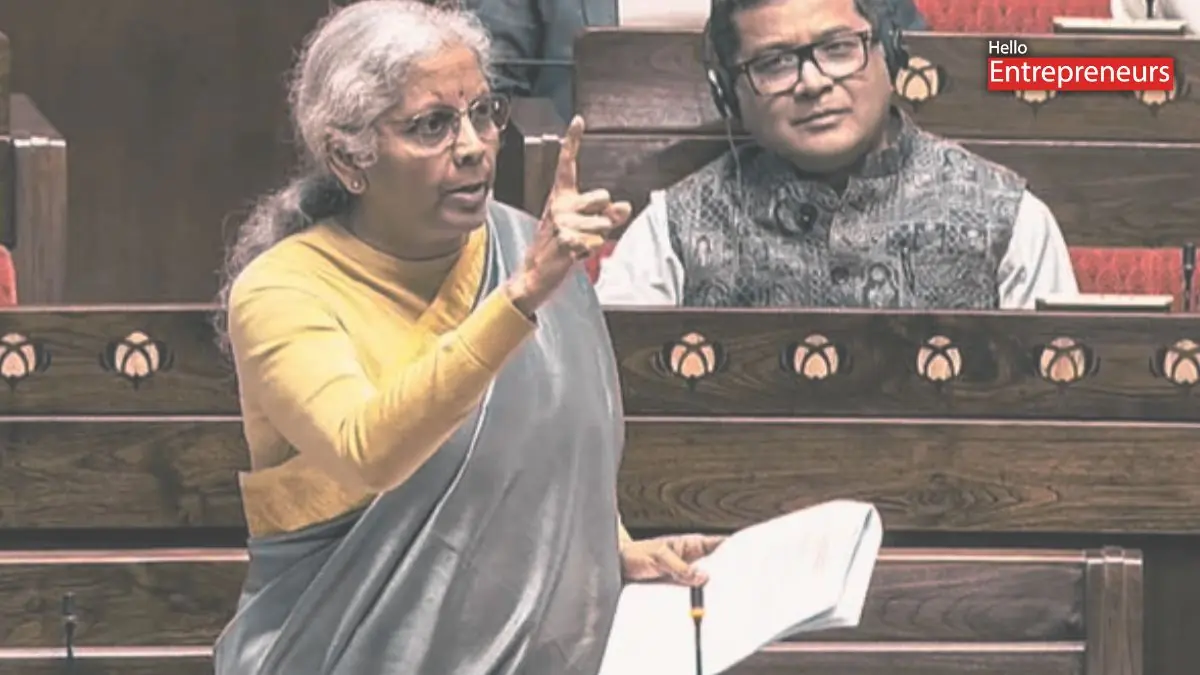





New Delhi: India’s Insurance sector could witness enhanced competition if Parliament passes the Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Bill, 2025, tabled on Tuesday, December 16 by Finance Minister Nirmala Sitharaman. This bill aims to ease regulations and boost competition in the insurance industry, which collected approximately $82.49 billion in premiums in FY25, a 5.6% increase from FY24.
FM @nsitharaman moves The Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Bill, 2025 in LokSabha.
The Bill further to amend the Insurance Act, 1938, the Life Insurance Corporation Act, 1956 and the Insurance Regulatory and Development Authority Act,… pic.twitter.com/Up1uBuWCf0
— SansadTV (@sansad_tv) December 16, 2025
Insurance industry snapshot
The industry has been growing at over 17% CAGR over the past two decades, driven by favourable regulatory changes, increased awareness and greater private sector participation.
Global players in the market are expected to deliver enhanced product diversity, technological innovation and improved customer service for policyholders by fostering healthy competition in the sector. The bill proposes amendments to three core legislations: the Life Insurance Corporation Act, 1956, the Insurance Regulatory and Development Authority Act, 1999 and the Insurance Act, 1938.
New features proposed
With this Bill, the government aims to boost investment in the sector by allowing 100% FDI from the 74% allowed currently, opening doors for foreign participants. One of the standout features proposed is the setting up of the Policyholders’ Education and Protection Fund (PEPF) that will be credited with grants, donations and penalties imposed by the IRDAI.
With greater competition, the bill also aims to boost IRDAI’s autonomy, while helping to improve the ease of doing business for insurers and other financial market stakeholders.
Reactions from the industry
Industry leaders have welcomed the move, stating it could help them foster innovation and competition in the industry. Various features of the bill, including composite licenses for life, health and non life products, lower capital requirements for insurers and abolishment of the exclusivity clause for insurance agents have been quite well received.
“The introduction of the Insurance Amendment Bill in the Lok Sabha, proposing to allow up to 100% FDI in the insurance sector, is a structural step that can meaningfully reshape India’s insurance ecosystem. Higher foreign participation is likely to bring in long-term capital, global underwriting expertise, and improved product innovation, all of which can support deeper insurance penetration across segments.” Hanut Mehta, CEO and Co-Founder at BimaPay Finsure, told Financial Express.
“As insurers gain access to larger balance sheets and global best practices, we can expect greater product diversification, higher ticket-size policies, and increased focus on corporate and MSME insurance,” he added.
The tabling of this Bill was part of the new-generation financial reforms proposed in the recent Union Budget, with the parliament expected to debate and deliberate on it, and hopefully give its approval for eventual implementation soon.